
A medical emergency abroad can turn a manageable trip into an expensive logistical challenge. If appropriate treatment is unavailable nearby, moving a patient to another hospital—or another country—can require specialist staff, monitoring equipment and a medically equipped aircraft. Emergency medical evacuation insurance addresses that transport risk, but its value depends on when a policy authorizes a transfer and where it will take you.
What emergency medical evacuation insurance actually covers
Medical evacuation coverage generally pays for medically necessary transport when suitable care cannot be provided at the patient’s current location. The destination is usually the nearest hospital capable of appropriate treatment, not necessarily one in the traveler’s home country. Some policies separately provide medical repatriation, arranging a return home after stabilization.
Travel medical insurance and evacuation insurance do different jobs. The first helps with eligible treatment bills; the second addresses eligible transport and coordination. A comprehensive travel policy may contain both benefits, while specialist evacuation plans can be purchased separately. Check whether your existing health insurance pays for emergency transport abroad.
Why evacuation costs can be so high
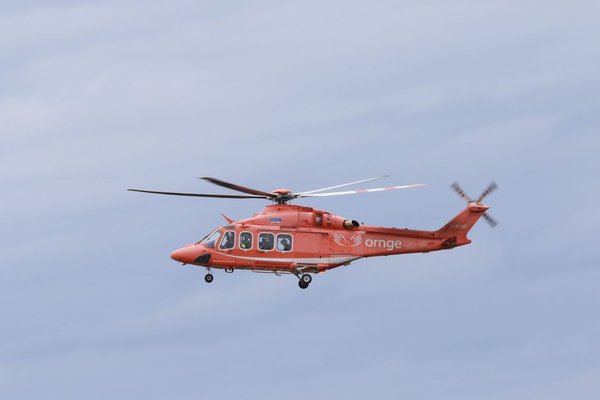
An evacuation is more than an airline ticket. The price may reflect air ambulance aircraft, medical professionals, oxygen, monitoring, ground ambulances, airport permissions and distance. Weather, patient stability and access to a receiving hospital can complicate arrangements.
The US Centers for Disease Control and Prevention’s 2026 Yellow Book describes medical evacuations costing about $25,000 within North America and exceeding $250,000 for some distant or remote transfers. These are illustrative figures, not standard prices or promised insurance payouts. The US Department of State also warns that an air ambulance back to the United States can cost tens or hundreds of thousands of dollars, depending on location and medical needs.
Not every patient needs a dedicated aircraft. Where medically appropriate, a commercial flight with a trained medical escort or stretcher may be used. Clinicians and the assistance provider assess what is safe; air ambulance insurance does not guarantee a private aircraft.
When a policy approves an evacuation
A serious diagnosis alone does not automatically trigger the benefit. The usual question is whether suitable treatment is available locally and whether transport is medically necessary. Insurers commonly rely on their assistance team and treating clinicians to evaluate the situation, choose a destination and organize a safe transfer.
Imagine a traveler injured while hiking on an island with a small hospital. Local clinicians stabilize a complicated fracture but cannot provide the necessary surgery. After consulting the hospital, the insurer’s assistance team may approve transfer to a regional trauma center. If that center can treat the injury, the policy may not pay to fly the traveler home, even if returning home feels preferable.
Evacuation to appropriate care, evacuation to a hospital of your choice and repatriation home are not interchangeable promises.
Which benefit limits deserve close attention?
Start with the evacuation benefit limit, but read beyond the headline amount. A generous-looking figure offers little protection if the policy excludes your destination, activity or medical condition. Check whether the limit applies per person, per trip or over the policy period, and whether separate caps apply to transport or repatriation.
Also establish whether evacuation costs share a combined ceiling with emergency medical treatment. A single pool can be reduced by an expensive hospital stay before transport begins. Some plans provide distinct medical and evacuation limits, making available protection easier to understand.
For a remote itinerary, ask whether the stated evacuation benefit limits realistically accommodate long-distance air transport. There is no universally adequate limit: healthcare access, route and patient needs all affect the expense.
Exclusions and approval rules that can change the outcome
Pre-existing conditions may be excluded unless the policy expressly covers them or a qualifying waiver applies. Adventure activities, altitude restrictions, pregnancy complications, alcohol-related incidents and travel against official government advice may also affect eligibility. Never presume a general promise of emergency cover includes every planned activity.
Another crucial condition is authorization. Many insurers require you or the treating hospital to contact the emergency assistance service before arranging a transfer. An independently booked flight or private evacuation may be refused even when the situation is serious. In an immediate emergency, seek local care first, then contact the assistance provider as soon as reasonably possible.
Review exclusions alongside your wider travel insurance coverage, especially if your plans include trekking, diving or destinations with limited hospitals.
How to compare policies before departure
Ask about the destination and assistance network
Confirm the policy covers every country and region on your route. For rural or offshore travel, ask how the provider coordinates transport from an isolated facility. The CDC recommends checking for a 24-hour physician-backed assistance center and arrangements for direct payment where available.
Check the route home, not just the route to treatment
Find out whether medical repatriation is included, whether it requires separate approval and what happens if you cannot use your original return flight. Ask whether a medically necessary companion, escort or dependent’s travel is covered; these extras vary between plans.
Get practical answers in writing
Compare the full policy wording, not only a comparison site’s summary. Record the emergency number, claims procedure, deductible and pre-authorization requirement. If you have an ongoing health condition, confirm its treatment under the policy before paying. A separate guide to travel insurance for pre-existing medical conditions can help frame those questions.
What to do if an evacuation may be needed
Obtain urgent local medical help and follow the clinician’s instructions. Ask a companion or hospital administrator to call your insurer’s assistance number, provide policy details and explain your diagnosis and location. Keep medical reports, hospital contacts and receipts, but let the medical and assistance teams coordinate transport whenever possible.
If approval or payment arrangements are unclear, request written confirmation of what the insurer will arrange and cover. A family member can help communicate, but clinical decisions belong with qualified professionals.
Frequently asked questions
Does regular travel insurance include emergency medical evacuation?
Sometimes. Many comprehensive plans include it, but the amount, destination rules and authorization process differ. Read the evacuation section rather than assuming medical treatment coverage includes transport.
Will evacuation insurance fly me back to my home country?
Not necessarily. Many policies authorize transfer to the nearest appropriate facility. Returning home may require a separate repatriation benefit or additional medical justification.
Is medical evacuation coverage worth considering for city trips?
Yes. Even in a major city, specialized transfer may be necessary, and domestic health coverage may not pay for international evacuation.
Can I arrange an air ambulance myself and claim later?
Do not assume so. Many policies require advance authorization and insurer coordination. Contact emergency assistance promptly unless urgent care makes that impossible.
Conclusion
Emergency medical evacuation insurance addresses a specific problem: getting a seriously ill or injured traveler to appropriate care when local treatment is insufficient. The most useful policy is not simply the one advertising the highest limit. It is the one whose medical-necessity rules, destinations, assistance arrangements and exclusions fit your journey. Read those details before departure, and keep the emergency number close throughout the trip.
